1The short version
2Side by side
| Arrive Home | Click n' Close SmartBuy | |
|---|---|---|
| Min. score | 600 | 640 forgivable · 660 repayable |
| First mortgage | FHA, 30-yr fixed | FHA 203b, 203(k) Limited, USDA, HUD-184 (closing-cost option: FHA 203b only). No conventional. |
| Forgivable | 3.5%, 0%, no payment. Forgiven at the borrower's request after 36 consecutive on-time payments. | 3.5%, 0%, no payment. Forgiven unless a 90-day late in the first 36 (3-yr) or 60 (5-yr) payments. |
| Repayable | 3.5% or 5%, 10-yr amortized at the first-mortgage rate + 2% | 3.5% or 5%, 9.99% fixed, 30-yr amortization, 10-yr balloon |
| Closing costs | Assistance can go to down payment, closing costs or prepaids (one amount) | The closing-cost repayable option can; the matrix doesn't say the others can |
| Buydowns | Not right now (temp buydown only with prior approval) | Permanent or 2-1 on all four purchase options (0.50% fee + price adjustment) |
| Fee on the second | $395 admin fee | $500 admin fee to REDCO |
Everything here is from the investors' current guidelines. Confirm on the live matrix for every file; terms change without notice.
3Market it: the agent flyer
Three styles, all cleared by compliance. Swap the house photos for ones that fit your market (or upload your own), drag them into place, and download. Your name, NMLS and licensed states fill in from My Profile.
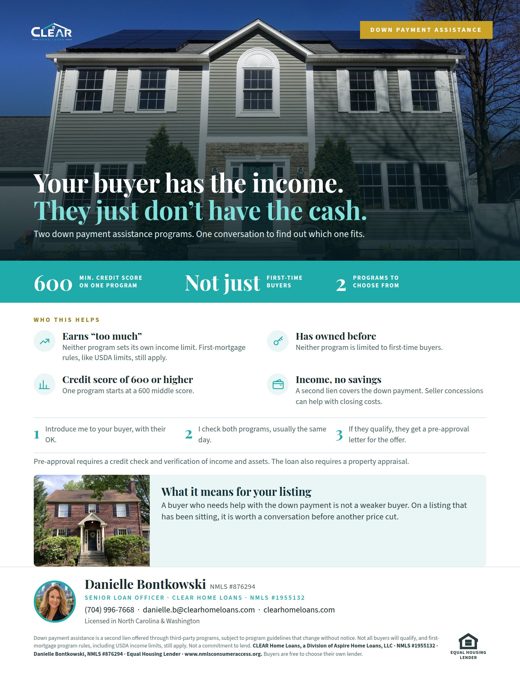
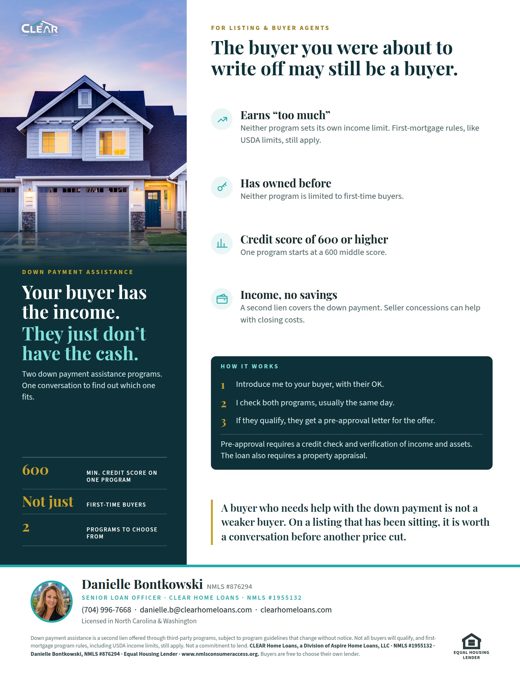
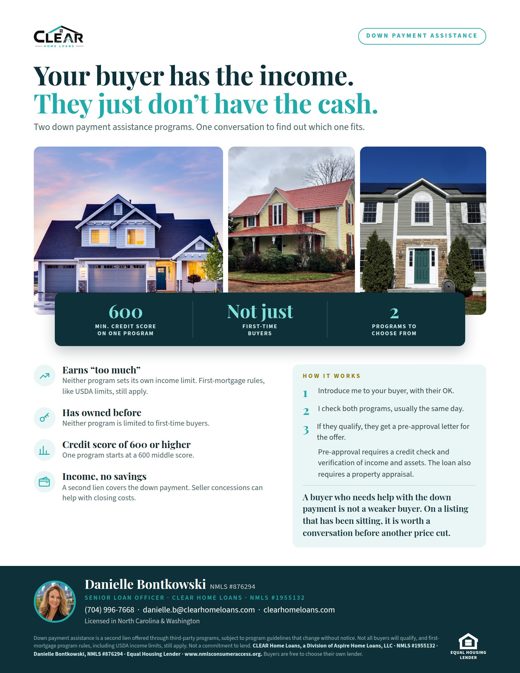
The wording and disclosures can't be edited. That's what keeps one compliance clearance good for everyone. Hand it to agents; don't post it as a consumer ad.
4Call script: listing agents
Best list to call: agents with listings that have been sitting. Say it in your own words; the facts below are the ones compliance cleared.
Opener
"Hi, it's [your first and last name] with CLEAR Home Loans. I'm calling agents about down payment help for their buyers. Quick question: do you have any listings sitting right now that you wish were moving faster?"
After they answer, then stop talking
"Here's why I called. I work with two down payment assistance programs. Neither one sets its own income limit, neither one is only for first-time buyers, and one goes down to a 600 credit score. So the buyer who has the income but not the savings, or who was told they make too much for help, may still be a buyer. Do you think that would help on that listing?"
Why a question and not a pitch: they start picturing the buyer who toured twice and never wrote. When they make the case, it's theirs.
If they're warm
"Can I send you a one-page flyer you can share with buyer agents? And if a buyer comes up, introduce me, with the buyer's OK, and I'll look at both programs for them."
If their listings are all moving
"Do you have any buyers who could handle the payment but don't have the down payment saved? Who comes to mind?" Then: "Have them reach out to me, or introduce us with their OK. I'll check both programs and tell them which one fits."
Voicemail
"Hi [name], it's [your name] with CLEAR Home Loans. I work with two down payment assistance programs for buyers who have the income but not the savings. If you've got a listing that's sitting, I'd like to send you a one-page flyer for buyer agents. I'm at [phone]. Again, [phone]."
Calling rules
Dial by hand and leave every voicemail yourself. No auto-dialers, voicemail drops or recorded messages. Call only agents in your licensed states. Call 8 a.m. to 8 p.m. their time, never on Sundays or holidays, and try no more than 3 times in 24 hours. Call office or listing numbers. Check a personal cell against the Do Not Call list first, unless the agent has worked with you or asked you to call. If anyone asks not to be called, stop and log it. Text an agent only if they've said it's OK.
If an agent asks who you are
"I'm [name], NMLS #[your NMLS]. CLEAR Home Loans is a Division of Aspire Home Loans, LLC, NMLS #1955132, an Equal Housing Lender."
The flyer you send afterward carries every ID in writing.
5Objections and answers
"What's the catch? Is it a second loan?"
"Yes, it's a second lien. The terms depend on the option, and I go over them with the buyer. The buyer still qualifies for the first mortgage the normal way."
"What about closing costs?"
"That's usually where the seller comes in. Seller concessions or other allowable sources can help with closing costs. On a listing that's been sitting, that's worth weighing against another price cut."
"My buyer makes too much for help."
"Neither program sets its own income limit. The first mortgage's rules still apply, so a USDA loan has its limits, but a buyer who was told they earn too much is worth a second look."
"Is it only for first-time buyers?"
"No. Neither program requires it."
"Can my seller buy the rate down too?"
"On one of the programs, yes. On the other it isn't available right now. Let me look at the file before you offer it to your seller."
"My buyer has a Section 8 voucher."
"Please introduce me. I'll sit down with your buyer, look at how their voucher works, and walk them through the options that fit."
"Will it slow down my closing?"
"The assistance is its own second loan with its own paperwork, so I build a little extra time into the closing date I give you. Tell me the contract date up front and we'll plan for it."
"Is it a grant?"
"No, it's a second lien. It has its own disclosures, so the buyer sees the terms before they sign."
6More ways to sell it
Teach the class
"Down payment assistance" is a 45-minute realtor class in Realtor Presentations, with speaker notes on every slide, in your choice of three styles. Offer it to an office that works with first-time and move-up buyers.
Email the flyer to an agent
Cleared by compliance. Attach your flyer, fill in the brackets, and send it one agent at a time. Keep the company lines, the address and the opt-out line at the bottom.
Who to call first
- Listing agents with homes sitting 45+ days. The flyer's "worth a conversation before another price cut" line was written for them.
- Agents who work with first-time and move-up buyers, and anyone who's mentioned a buyer who "makes too much" for local programs.
- Your own agents are in My Agents; ready-made lists are in Agent Call Lists on the Toolkit home page.
7Watch-outs and who to call
- Arrive Home + a buydown: don't promise both. Buydowns aren't currently acceptable (CLG 3.26.16). If the seller wants to pay for a buydown, that's a Click n' Close file, and it counts toward the seller-concession limit.
- The second lien is a full second file on both programs: its own loan number, application, LE, CD and disclosures. Build the time into the closing date you give the agent.
- Section 8 vouchers: Arrive Home doesn't accept Section 8 vouchers. We still offer Arrive Home. If a buyer has one, never turn them away. Meet with them, check whether they and their voucher fit Click n' Close or another program's guidelines, and walk them through every option that fits. Don't share this with agents.
- Arrive Home repayable: the borrower watches the program video before closing. Credit refresh within 10 days of closing.
Same team: Katelyn Duffy, Eloy Benavides.
arrivehome.org › Lender › Lender Resources has the current matrix and guide.
jason.goodman@clicknclose.com
Price in Arive, LoanSifter or their own system. Ask Jason for the current matrix.