★Start here: get your builder list
Tell us where you want to work. You get the full builder kit in your inbox right away, and a researched list of local builders to call within a couple of hours.
1What it is and who it's for
Buyers aren't walking away from the price. They're walking away from the monthly payment. A forward commitment lets a builder buy down the rate on a block of homes in advance. Every qualified buyer who locks on those homes gets that rate for the life of the loan, and the list price never moves.
On a $968,500 home, getting the buyer to the same payment costs about $32,030 to buy the rate down for good, from 7.75% to 6.75%, against a $91,676 price cut. A price cut costs nearly three times as much, and it resets the comp on every home the builder still has to sell.
2Learn it
How it works
- Pick the homes. The builder's standing inventory and a target rate.
- Fund it up front. Points on the pool, priced by Capital Markets on the day of the trade.
- We lock the trade. Capital Markets buys that pricing the same day. It's a real position in the market.
- Buyers lock in. A permanent rate for the life of their loan.
Because the pricing is bought as a bulk trade before any buyer exists, it is treated differently from a seller concession. Depending on the loan program and investor guidelines, it may not count toward the buyer's interested-party contribution limit — which can leave room for closing-cost credits on top. Treatment is confirmed on each loan, so never promise it flat. A temporary 2-1 can be layered on as well. That part is a seller concession and counts toward the limit.
Pair-off: the question every builder asks
Pair-off is not a penalty. It's the unwind of a trade that didn't get used, and it only costs the builder when both of these happen:
"When we set this up, we buy that pricing that day. It's a real trade. If you sell the homes, none of this comes up. If you come up short and rates fell in the meantime, the part you didn't use is unwound at the new market, and that difference passes through. On the unused part, never the whole pool."
Size the pool so it never comes up
- Commit to the floor, not the forecast. Size it to a bad quarter. They can always come back for a second pool.
- Standing inventory first. Homes that exist deliver.
- Short window on a first trade. A window they beat builds the relationship.
- Ask who else sells their buyers. If a preferred lender takes half the buyers, half the pool won't deliver.
Get from Capital Markets before any builder signs
The tolerance band (how far under they can land with no pair-off), how pair-off is calculated and when, the window and any extension fees, and how unused points refund. Dave Bennett models the community and prepares the Bulk Trade Agreement. You don't fill it in.
Words that lose the room
- "Penalty." It's an unwind at market, not a penalty.
- "You get all your points back." Unused points refund, less any pair-off. Always say both halves.
- Quoting a pair-off number. It doesn't exist until the day it's measured. "I'll have Capital Markets model that for you" is the strong answer.
- "Almost three times." The approved phrase is "nearly three times." And say "permanent" for the commitment, "temporary" for a 2-1.
When to pivot to a one-at-a-time buydown
Any two of these: fewer than about six homes a year · no sales office or listing agent · one or two finished homes at a time · they can't name what's closing in the next 90 days. The one-at-a-time kit is being updated; ask Christa.
3Tools
The tool makes both documents, and it puts your details on them — name, title, NMLS, phone, email and headshot, filled in from your CLEAR profile. Nobody else's details ever print; a blank field prints as an amber box and printing stays locked until you fill it.
- Builder partner package (3 pages) — enter the builder, how many standing homes, the average price, down payment, the CLEAR standard rate and how far to buy the rate down.
- Spec-home flyer (1 page) — the same numbers plus the address, beds, baths, square feet, the builder's phone and a photo of the home. The photo is required on this one; it is a photo piece.
The samples below are built for New Leaf Builders with Christa's details, so you can see the finished set. Make your own in the tool — don't hand out the samples.
The comparison rate is CLEAR's own 30-day-lock par pricing for the scenario, not a survey average, and the pages label it "CLEAR standard rate" for that reason. Points fill in from the 9/29 pricing ladder; replace them with today's price for your scenario. Never show a builder a par or break-even price.
4Market it
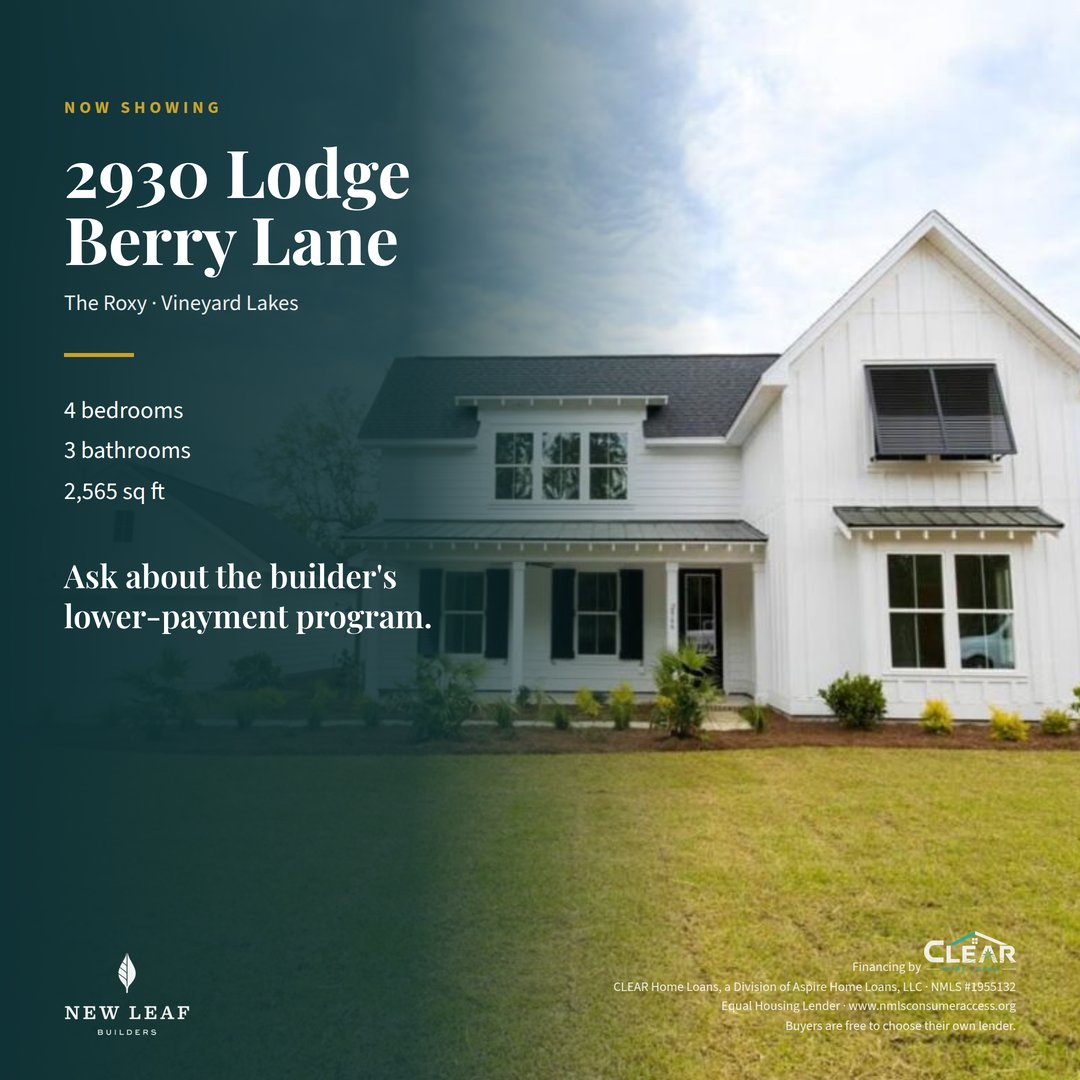
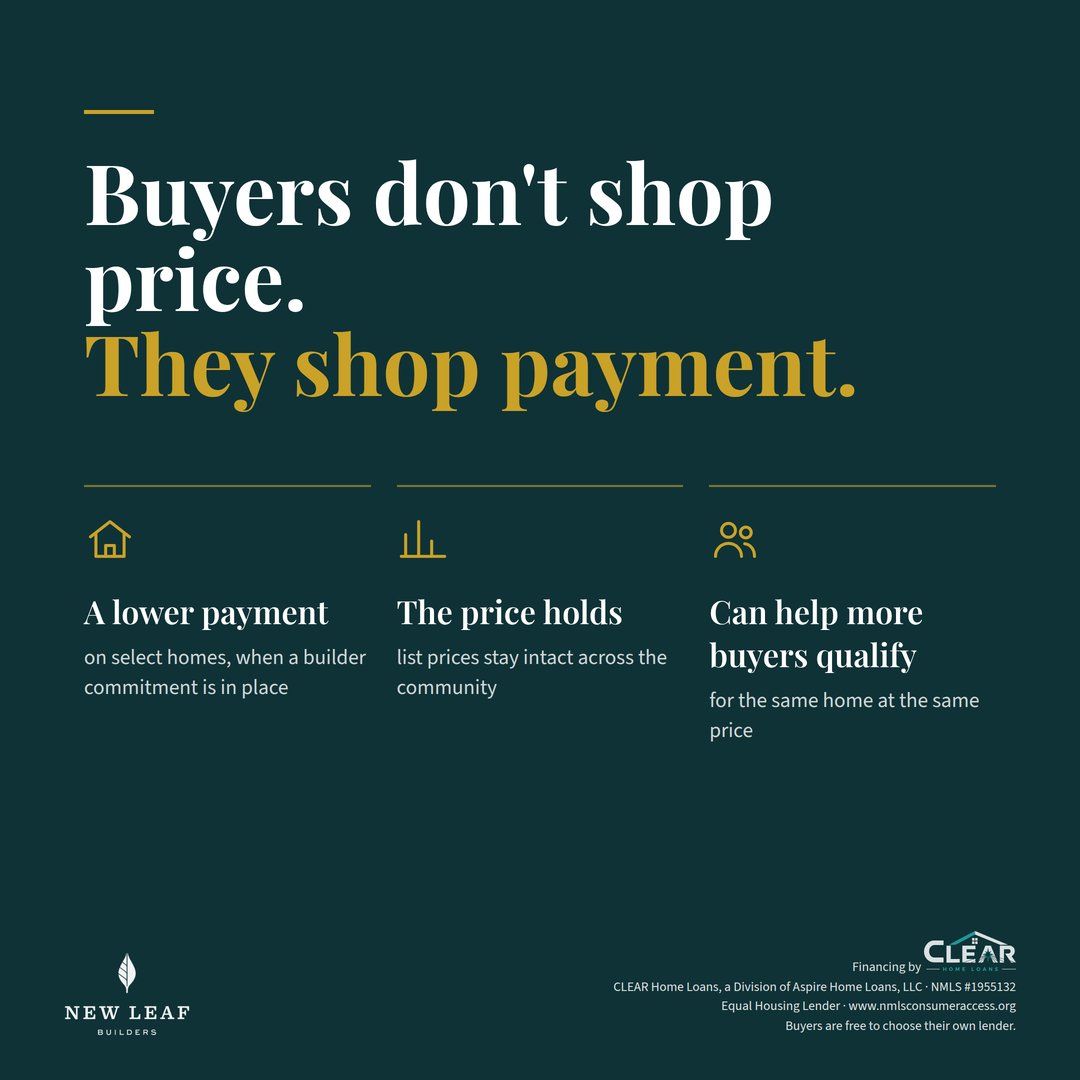
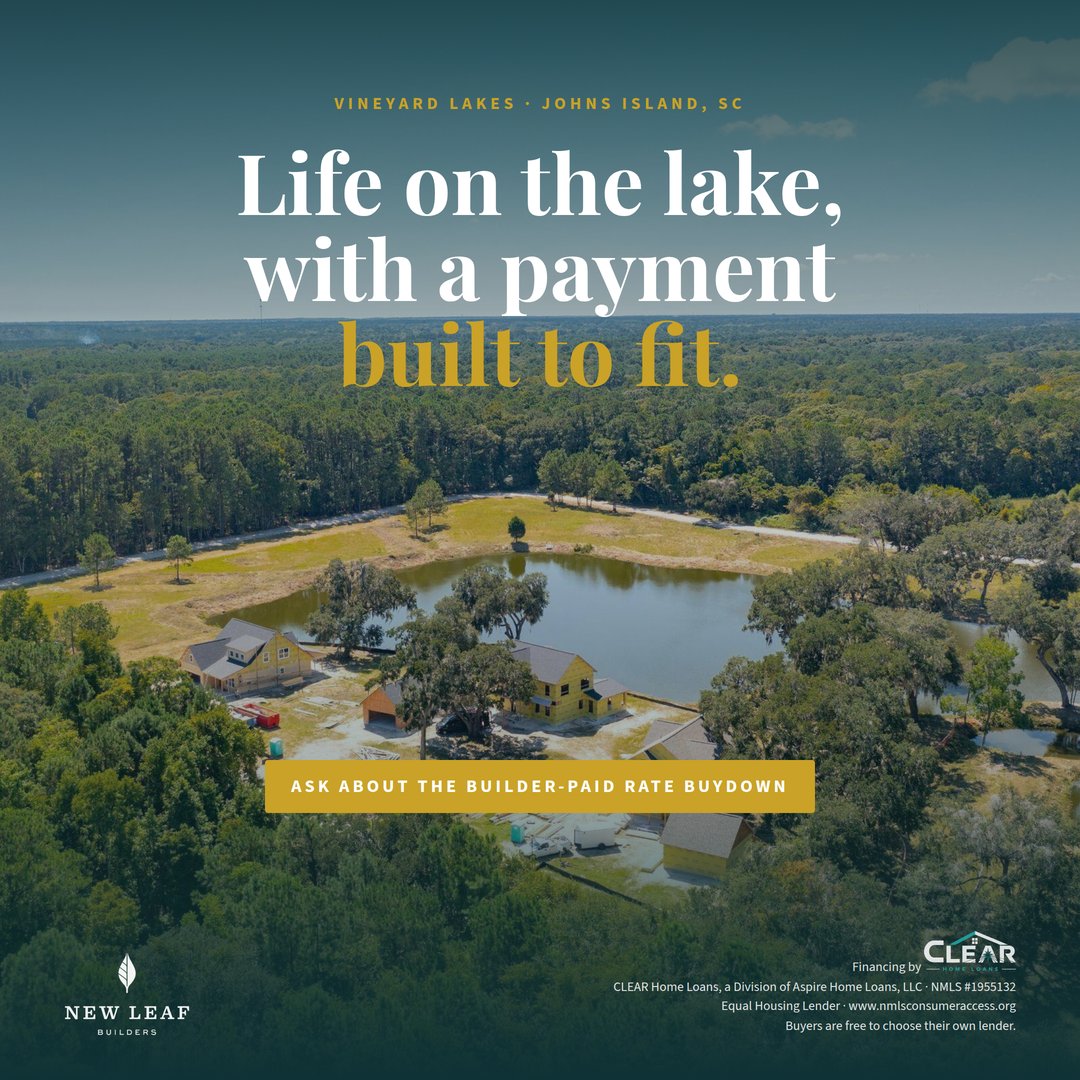
Samples built for New Leaf Builders at Vineyard Lakes, so you can see the finished set. Make your own builder's package in the tool above.
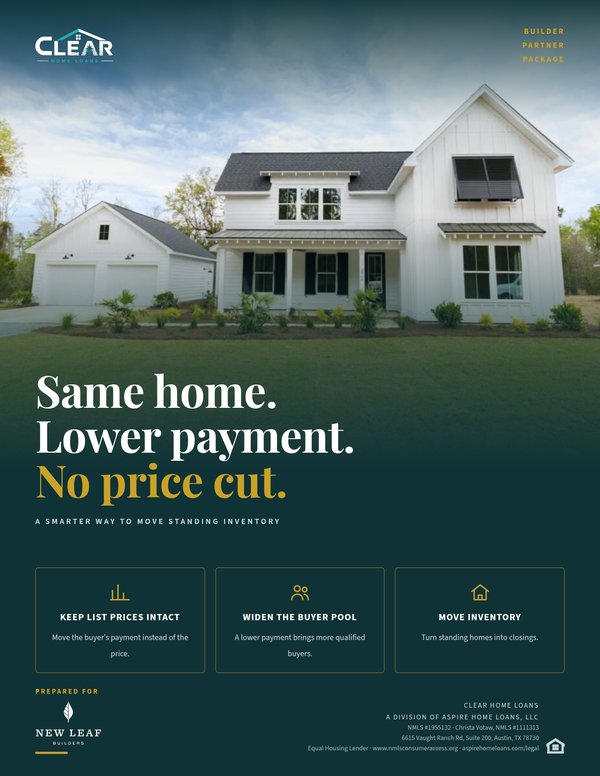 Builder package, 3 pagesCover · the numbers · how it works
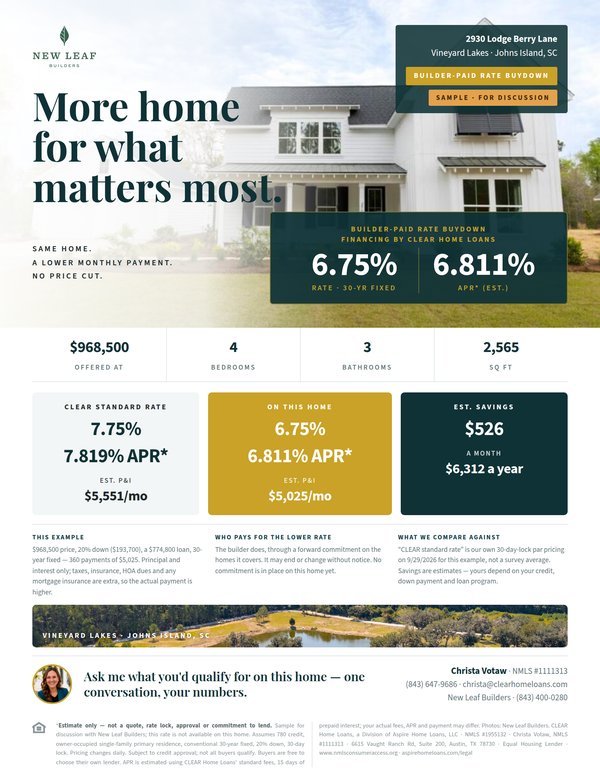 Spec-home flyerFor the home itself, rate and estimated APR
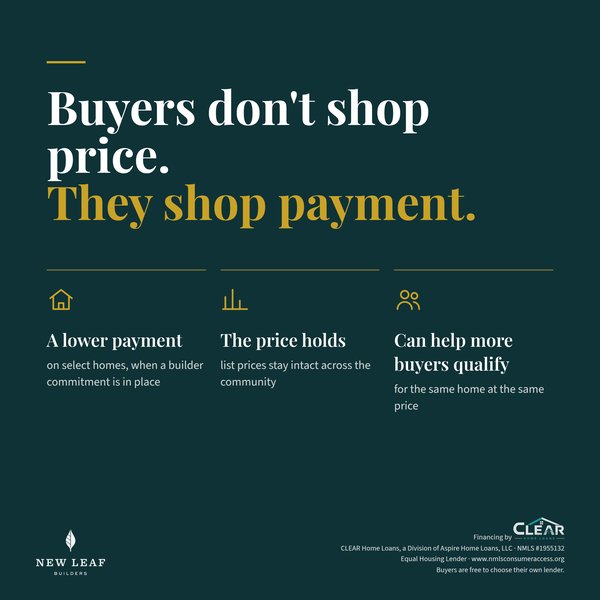
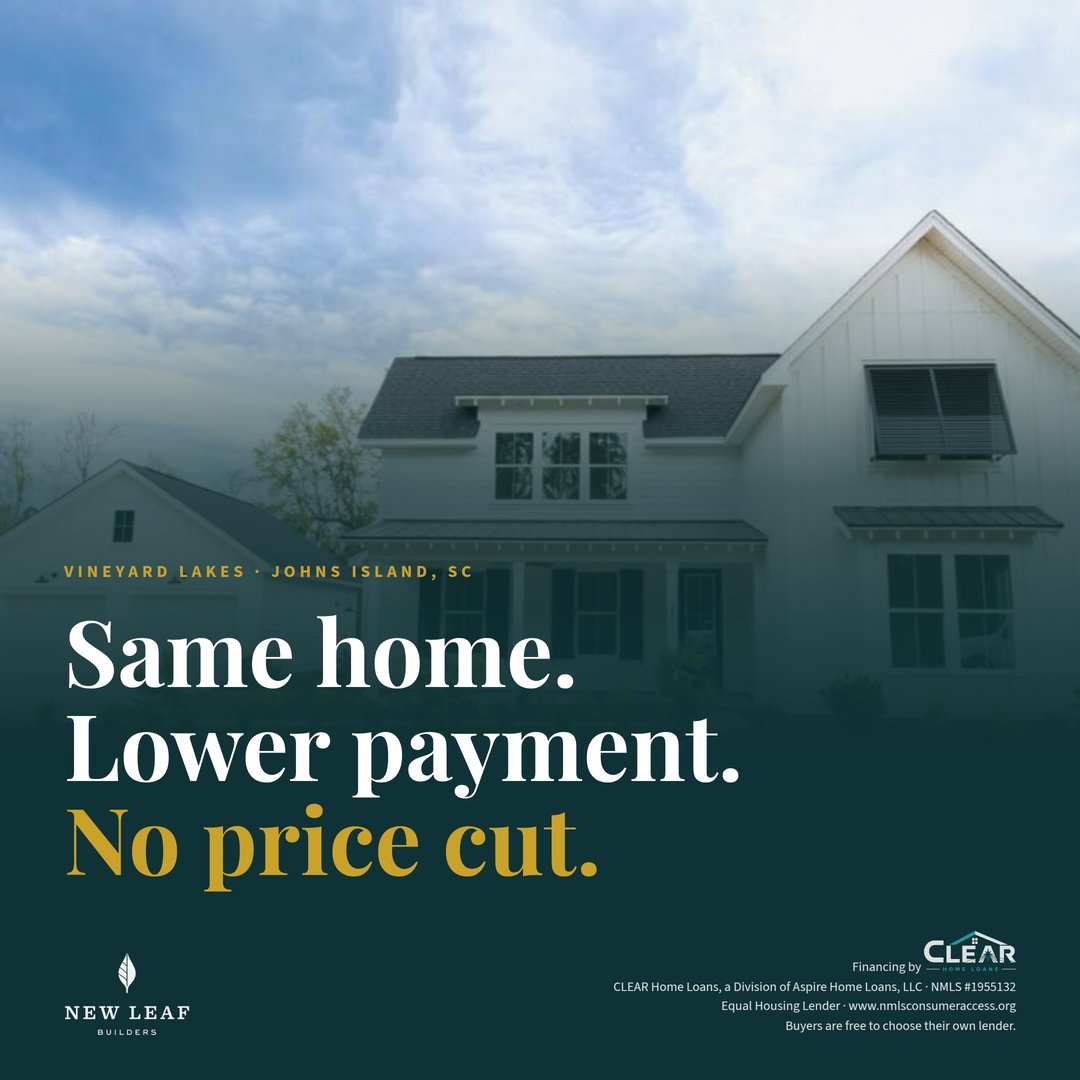 Social posts for the builder4 posts, no rates or payments
 Suggested captionsWith the lender line every post needs
More posts: post 2 · post 3 · post 4. Social posts never state a rate or a payment amount.
5Compliance and contacts
- Ready to use. The builder package, spec-home flyer and posts are ready to send to builders. Every rate carries its APR and every page carries the required disclosures, so don't edit or remove them.
- Never guarantee a rate, price, APR or availability, and never call it a commitment to lend.
- Never promise the buydown is outside the buyer's concession limit. Say it may not count toward interested-party contribution limits depending on loan program and investor guidelines, and that treatment is confirmed on each loan. FHA and many investors do count builder-funded buydowns.
- Don't sell it as comp protection. Talk about the list price holding and the buyer's payment dropping. An appraiser must treat the buydown as a financing concession, and it has to be disclosed in the purchase contract.
- Unused points refund net of pair-off, which can be significant if rates decline. Never say "you only pay for what you use."
- Buyers are always free to choose their own lender. Never tie a builder incentive to using CLEAR (RESPA).
- Same terms for every qualified buyer (fair lending). Any rate shown to consumers carries an APR at least as prominent as the rate.
| Who | For |
|---|---|
| Dave Bennett, Capital Markets | Modeling a community, pricing the trade, the Bulk Trade Agreement, pair-off terms |
| Christa Votaw, National Sales Director | The program, the pitch, and anything on this page |
| Compliance | Approval of any piece before it goes to a builder or a buyer |